Managing law firm finances requires precision, but few operational areas cause as much confusion—or audit exposure—as advanced client costs in QuickBooks. Whether your firm handles high-stakes personal injury litigation, complex estate planning, or corporate defense, advancing capital on behalf of clients is a routine reality. From filing fees and court reporters to expert witness retainers and medical record fees, legal practices routinely disburse substantial sums expecting full reimbursement at settlement or trial conclusion.
However, many attorneys and legal bookkeepers make a catastrophic mistake: they treat these client disbursements as ordinary deductible operating expenses on their Profit & Loss (P&L) statement. Under longstanding IRS rules and federal tax court precedents, advancing litigation costs is legally classified as an interest-free loan to the client—not an immediate tax deduction. Misclassifying these payments artificially depresses your taxable income, distorts your true profitability, and creates severe tax penalties during an audit.
To keep your firm fully compliant, profitable, and audit-ready, you must establish an airtight workflow for handling both hard costs and soft costs. In this guide, we break down the critical IRS standards governing client disbursements and reveal the 5 crucial rules for recording and managing advanced client costs in QuickBooks.
Table of Contents
What Are Advanced Client Costs in Legal Financial Management?
Advanced client costs—frequently referred to as client reimbursable expenses or matter costs—are expenses incurred by a law firm on behalf of a specific client matter that the client is contractually obligated to reimburse. These costs arise across all billing models, including hourly billing, fixed fee engagements, and contingency fee litigation.
Unlike internal firm overhead (such as office rent, staff payroll, or software subscriptions), advanced client disbursements are paid directly for the client’s benefit. Because the firm anticipates recouping these funds when the matter settles or an invoice is paid, financial management for them requires strict separation from general operational overhead. If you already practice strict trust financial management compliance as outlined in our guide on three-way IOLTA reconciliation, understanding matter cost tracking is the essential second pillar of your practice’s financial health.
Hard Costs vs. Soft Costs: The Critical Distinction
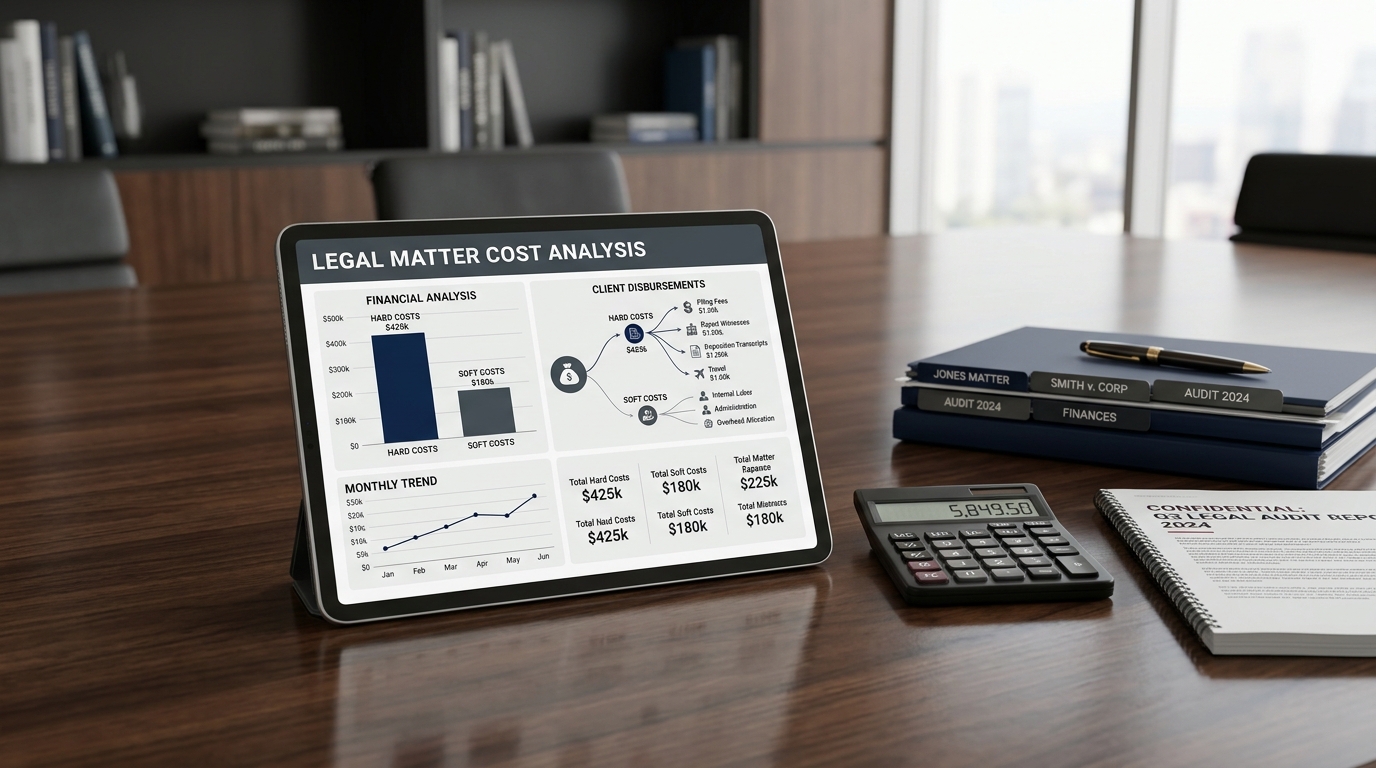
A fundamental requirement of legal financial management is distinguishing between hard costs and soft costs. These two categories have drastically different tax implications and financial management treatments in QuickBooks:
- Hard Costs (Direct Third-Party Disbursements): Tangible, out-of-pocket payments made directly to third-party vendors exclusively for a client’s matter. Common examples include court filing fees, deposition transcripts, process server fees, expert witness retainers, medical record retrieval charges, and specialized trial exhibits. Because money flows directly from your operating account to an outside entity for a client’s case, hard costs must be capitalized as an asset.
- Soft Costs (Indirect In-House Allocations): Internal firm expenses allocated or billed back to a client matter. Examples include internal document copying (billed at $0.20 per page), postage and shipping meters, specialized legal research software usage (such as Westlaw or LexisNexis), and long-distance telephone calls. These are overhead costs your firm has already paid and deducted as ordinary operating expenses; billing them to the client constitutes firm income rather than an asset recovery.
The IRS Tax Trap: Why Advanced Client Costs Are Not Immediate Expenses
The single most dangerous misconception in law firm bookkeeping is expensing hard costs immediately on the P&L statement upon payment. Many attorneys assume that because cash leaves the firm’s operating checking account, it qualifies as an ordinary business deduction under 26 U.S. Code § 162 (Trade or Business Expenses).
The Internal Revenue Service strictly disagrees. Established through foundational tax court cases such as Canelo v. Commissioner (53 T.C. 217) and Boccardo v. Commissioner (56 F.3d 1016), the law dictates that when an attorney advances litigation expenses with an expectation of reimbursement, the transaction is treated as a loan from the firm to the client. Consequently, the firm cannot take an immediate tax deduction in the year the payment is made.
If your firm expenses $100,000 in advanced litigation hard costs across several active cases this year, you cannot reduce your firm’s taxable profit by $100,000. Doing so understates your taxable income. In the event of an IRS audit, the agent will disallow the deductions, add $100,000 back to your taxable net income, and assess significant back taxes, interest, and accuracy-related penalties.
5 Essential Rules for Advanced Client Costs in QuickBooks
To satisfy both IRS tax regulations and state bar ethical rules (including ABA Model Rule 1.15), follow these 5 proven rules when tracking advanced client costs in QuickBooks.
Rule 1: Create an Other Current Asset Account on Your Balance Sheet
Do not record hard client costs in an expense account like “Legal Supplies” or “Court Costs.” Instead, set up a dedicated asset account in your Chart of Accounts:
- Account Type: Other Current Assets
- Detail Type: Other Current Assets (or Loans to Others)
- Account Name: Advanced Client Costs (or Client Reimbursable Expenses)
When you write a check, swipe an operating credit card, or issue an electronic funds transfer for a client filing fee, debit this Advanced Client Costs asset account. This accurately reflects that the firm owns an asset—a receivable loan due from the client—without touching your P&L statement.
Rule 2: Link Every Disbursement to a Specific Client Matter
Every dollar paid into the Advanced Client Costs account must be explicitly assigned to a specific Client:Matter sub-customer in QuickBooks. Never record a lump-sum disbursement without matter tagging.
When recording an expense or bill in QuickBooks Online, ensure the “Customer / Project” field is populated with the exact matter name. If your practice utilizes legal billing software such as Clio, LeanLaw, or MyCase, verify that expense sync mappings route directly into this asset account and attach to the active matter ledger.
Rule 3: Treat Hard Costs and Soft Costs with Distinct Workflows
Because soft costs are internal overhead recoveries rather than third-party advances, their financial management path is completely different:
- Hard Costs: Funded from the firm’s Operating Account (never IOLTA), debited to the Advanced Client Costs Asset account. Zero P&L impact upon disbursement.
- Soft Costs: Paid as regular overhead (e.g., office copier lease, postage supplies), debited to standard Expense accounts on the P&L. When billed to the client, the charge is credited to an Income account titled Soft Cost Reimbursements / In-House Recoveries.
Confusing these two workflows can distort your operational gross margin and trigger financial management red flags during a compliance review. If you need assistance configuring your Chart of Accounts, our specialists in QuickBooks troubleshooting and cleanup can structure your books correctly.
Rule 4: Invoice and Reimburse Without Inflating Firm Revenue
When you invoice the client or deduct reimbursed expenses from a settlement payout, you must not record the reimbursement as legal fee income. If you advanced $5,000 for expert witnesses and invoice the client $5,000 to recover it, recording that $5,000 as legal fee income artificially inflates your gross receipts.
In QuickBooks, create a Product/Service item named Advanced Client Cost Reimbursement. Map this item directly to your Advanced Client Costs asset account—not an income account. When the client pays the invoice or settlement funds are distributed, QuickBooks automatically credits the asset account, reducing the outstanding client balance back to zero.
Rule 5: Reconcile Advanced Client Costs Monthly Against Matter Ledgers
Just as state bar rules require monthly reconciliation of trust liability accounts as detailed in our guide to IOLTA trust account bookkeeping, your general ledger asset balance must be reconciled against your individual matter cost ledgers every 30 days.
Generate an Unbilled Costs by Job report or run a Balance Sheet detail in QuickBooks. The total balance of your Advanced Client Costs asset account must equal the sum of unbilled or unrecovered costs across all open client matters. Any variance indicates missing receipts, unassigned expenses, or double-billed items that must be resolved immediately.
Common Advanced Client Cost Mistakes That Trigger Audits
Even seasoned legal administrators frequently stumble into costly pitfalls when managing matter disbursements. Avoid these four common traps:
- Paying Hard Costs from the IOLTA Account Without Retainer Funds: Never write a check from your IOLTA account for a filing fee or expert retainer unless that specific client has sufficient cleared trust funds sitting in their individual ledger. Borrowing funds held for Client A to pay costs for Client B is an ethical violation and grounds for disciplinary action.
- Ignoring Uncollectible Client Costs: In contingency cases where a case is lost or settlement is insufficient to cover expenses, the advanced cost transforms from an asset into a bad debt. Only when a case is officially closed without recovery may the firm write off the balance sheet asset as a deductible bad debt expense.
- Failing to Collect Receipts for Matter Expenses: The IRS demands substantiation for every dollar advanced. Ensure digital receipts and invoices from court reporters, process servers, and expert witnesses are attached directly to the QuickBooks transaction.
- Mixing Personal or Firm Overhead with Matter Costs: Meals, parking, or mileage incurred during travel must be carefully segregated based on the client engagement letter. Only billable matter costs directly authorized by client contract should be capitalized.
Master Your Legal Financial Management and QuickBooks Setup with RPPC
Tracking advanced client costs in QuickBooks requires an financial management framework that seamlessly bridges IRS tax compliance, state bar ethical mandates, and daily billing workflows. Without proper systems, managing partner profits remain murky and tax audit vulnerabilities quietly multiply.
At RPPC Financial Management Firm, our certified legal financial management specialists help law firms throughout Missouri, Kansas, and across the nation optimize their financial architecture. From customized QuickBooks Chart of Accounts design and legal software integrations to monthly three-way trust reconciliations and virtual CFO leadership, we ensure your firm stays protected, audit-ready, and maximally profitable.
Discover how our expert law firm financial management solutions can streamline your financial operations and safeguard your bottom line.